Critical illness
A qualifying diagnosis like a heart attack, stroke, or cancer can unlock a portion of your benefit to cover treatment, travel, or the mortgage while you recover.
Mortgage protection that pays your family directly, so the house stays theirs. Living benefits if you get seriously ill. And tax-advantaged ways to grow money you can use during your lifetime.
We shop coverage across carriers like
The mortgage doesn't pause when a paycheck stops. Here's what American households say about their own coverage.
Nearly half of U.S. consumers say they would face financial hardship within six months if their primary wage earner passed away unexpectedly.
overestimate what basic term life insurance costs. Most people guess high, so they never even get a quote.
American adults say they need life insurance or need more than they have.
Source: LIMRA and Life Happens, 2024 Insurance Barometer Study.
Mortgage protection is life insurance built around your home loan. It pays your family directly and they decide how to use it. There are two main ways to design it, and plenty of families use a mix of both.
Your coverage matches your mortgage balance and stays level for the life of the loan. If you pass away, your family can pay the house off completely and never make another payment.
Your loan balance goes down with every payment while your coverage amount stays level. Each year the difference between the two gets bigger, and that difference goes to your family on top of the payoff.
Example: $350,000 loan at 6.5% for 30 years
A critical period plan covers a set stretch of mortgage payments, usually 12 to 36 months. That's the critical period: the months right after a loss when your family is grieving, adjusting to one income, and at the highest risk of missed payments or a rushed sale.
The policy keeps the payments going, which protects the equity you've built and gives your family time to decide whether to keep the house, sell it on their own terms, or refinance. Because the coverage amount is smaller, the premium is usually lower too.
Example: $2,212 monthly principal and interest
| Side by side | Full payoff | Critical period |
|---|---|---|
| What it covers | The entire mortgage balance | A set number of monthly payments (often 12 to 36) |
| Monthly cost | Higher, since the coverage amount is larger | Lower, since the coverage amount is smaller |
| Your family's options | Own the home free and clear, with money left over as the balance drops | Time to keep, sell, or refinance without losing equity to a rushed decision |
| Best for | Single-income households, young kids at home, anyone who wants zero mortgage risk | Tighter budgets, dual incomes, and homeowners with meaningful equity |
Move the sliders to match your mortgage. You'll see both coverage designs side by side. No email required.
A critical period plan covers about 16% of the coverage amount of a full payoff plan.
Your actual price depends on your age, health, tobacco use, and the carrier. Many families compare both, then land somewhere in between.
Get real quotes for bothOld-school life insurance only paid out if you died. Many of today's policies let you access part of your death benefit early if a serious illness or injury hits, when the bills are piling up and a paycheck may have stopped.
A qualifying diagnosis like a heart attack, stroke, or cancer can unlock a portion of your benefit to cover treatment, travel, or the mortgage while you recover.
If you can no longer do two of the six daily living activities on your own, like bathing or dressing, you may be able to draw from your benefit to pay for care.
With a terminal diagnosis, a large part of the benefit can often be paid early, so your family can focus on time together.
Living benefit riders, triggers, and payout amounts vary by carrier, product, and state. Accelerated benefits reduce the death benefit.
The number one objection to term insurance is "what if I pay for 30 years and never use it?" Return of premium plans answer that. If you outlive the term, many of these policies refund the base premiums you paid. It costs more each month, but it works like a forced savings plan wrapped around your protection.
Every dollar you save lands in one of three tax buckets. Most families have almost everything in the first two, which means a tax bill waiting for them in retirement. The third bucket is where cash value life insurance lives.
An IUL is permanent life insurance with a cash value account. Your cash value earns interest based on how a market index like the S&P 500 performs. The money itself is never invested directly in the stock market.
In good years your policy is credited interest based on the index. Many strategies cap that interest, but with the right carrier and index choices, some have no cap at all, so your upside is potentially uncapped. In down years the 0% floor means index losses aren't credited to your account.
Hypothetical index returns on an uncapped strategy with a 0% floor
For illustration only. Not a projection or the performance of any product. Uncapped strategies are usually tied to volatility-controlled indexes and may use participation rates or spreads that affect crediting. Other strategies have caps. Rates, fees, and charges vary and can change. IUL is not a direct investment in the market or any index. Policy charges still apply in 0% years, so cash value can decrease if a policy is underfunded.
Every time you finance a car, a renovation, or a business purchase, you pay interest to a bank. With infinite banking, you build cash value inside a policy designed for it, borrow against it when you need money, and pay yourself back on your own schedule.
A whole life or IUL policy designed to put as much of your premium as possible into cash value.
Steady, guaranteed growth plus potential dividends with whole life, or index-linked growth with a floor with IUL.
Use a policy loan for a car, a down payment, inventory, or an emergency. No bank application and no credit check.
Repay on your terms, restore your cash value, and do it again. With the right design, your full cash value keeps working even while a loan is out.
The traditional infinite banking vehicle. Guaranteed cash value growth, potential dividends from a mutual carrier, and fixed premiums. Predictable and steady, built for people who want certainty.
Index-linked growth with a 0% floor, flexible premiums, and more upside potential. More moving parts, so the design and ongoing reviews matter even more.
Policy loans accrue interest and reduce cash value and the death benefit until repaid. Excessive loans or underfunding can cause a policy to lapse, which may create a tax bill. Policies funded above IRS limits become modified endowment contracts (MECs) and lose some tax advantages. Cash value takes time to build. Dividends are not guaranteed.
Pick a time that works. We talk about your home, your family, and what you want the coverage to do.
We compare 10+ carriers and design the coverage around your goals and budget.
Many policies are approved within days and many need no medical exam. You'll know exactly what you have and what it costs.
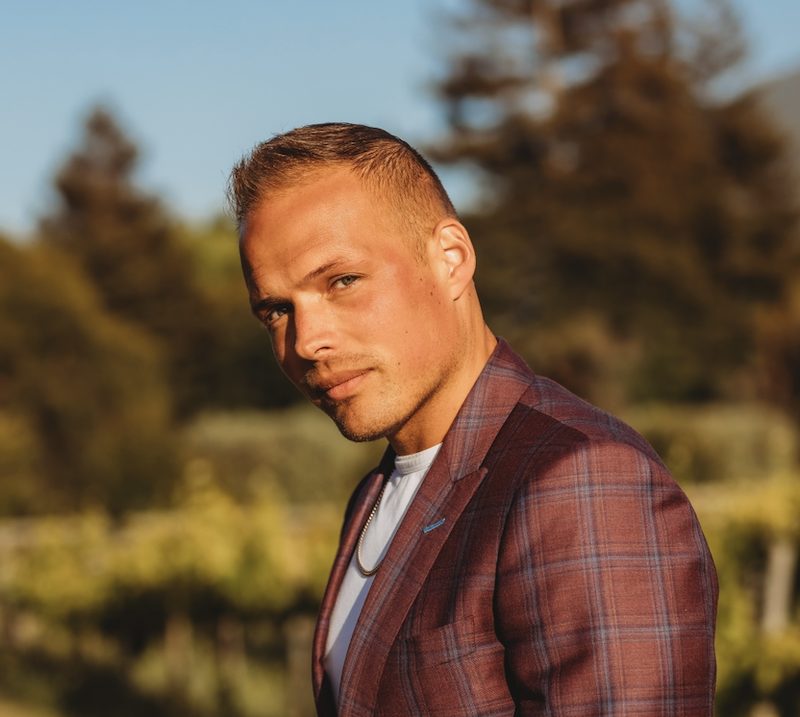
Founder and Licensed Insurance Producer, NPN 22308775
I got into this work for a personal reason. When my father passed away, my family was on the receiving end of a life insurance policy. I saw what that protection meant for the people he left behind, and I've carried that with me ever since.
That's also where our name comes from. Kindred means your people, the ones you would do anything for. A legacy is what you leave them. Kindred Legacy Life exists to make sure the families I work with are taken care of the way mine was.
As an independent agent, I work with more than 10 carriers and match each family with the coverage that fits their home, their budget and their goals. I'm based in Las Vegas and work with families nationwide by phone and video.
No. The private mortgage insurance (PMI) your lender requires protects the lender if you default. Mortgage protection life insurance pays your family directly, so they can pay off the home, cover payments, or use the money however they need. You own the policy, and your family is the beneficiary.
It depends on your budget, your equity, and who depends on your income. A full payoff plan removes the mortgage completely. A critical period plan covers a set number of payments so your family has time to decide what to do without losing equity to a rushed sale, usually for a lower premium. On our call we'll quote both so you can see the difference in real dollars.
Often, no. Many of our carriers offer coverage based on a short health questionnaire and a prescription history check. Some situations or larger coverage amounts may still require an exam, and we'll tell you up front if that applies to you.
It depends on your age, health, tobacco use, the coverage amount, and the type of policy. Most people guess much higher than the real number. Because we quote multiple carriers, you'll see options at different price points and choose what fits.
The floor protects your cash value from index losses, so a down market year credits 0% instead of a negative number. But the policy still has costs of insurance and fees that come out every month. If a policy is underfunded or over-borrowed, cash value can shrink and the policy can lapse. That's why design, consistent funding, and annual reviews matter, and why we walk through the illustration line by line with you.
It's a real strategy, and it takes patience. It works when a policy is designed for high cash value, funded consistently, and used with discipline. The first few years build the foundation. We'll be straight with you about whether it fits your situation, or whether a simpler plan makes more sense right now.
Like any licensed insurance producer, we're paid by the insurance carrier when a policy is issued. Your premium is set by the carrier and is the same whether you use an agent or not.
It's smart to ask. If you got a call, text, or letter from us, it's because you or someone in your household requested information about mortgage protection or life insurance. Sam Holmes is a licensed insurance producer, NPN 22308775, and you can verify that license with your state's department of insurance. We're not affiliated with your lender, and we will never ask for payment over the phone to "reserve" a rate.
Yes. Every policy has a free look period, typically 10 to 30 days depending on your state, when you can cancel for a full refund. After that you can cancel any time. If your needs change down the road, we'll help you adjust your coverage.
Your call takes about 15 minutes. Once Sam knows your health, age, and specific needs, he'll guide you to the best options to protect your home and family.
Share a few details and Sam will put together options from multiple carriers, matched to your home and your goals.